Every preceding generation was raised on the same principle of saving whatever is left after all essential needs have been fulfilled, and investing what remains. It sounds logical. However, a growing number of Generation Z individuals prefer to flip this principle over.
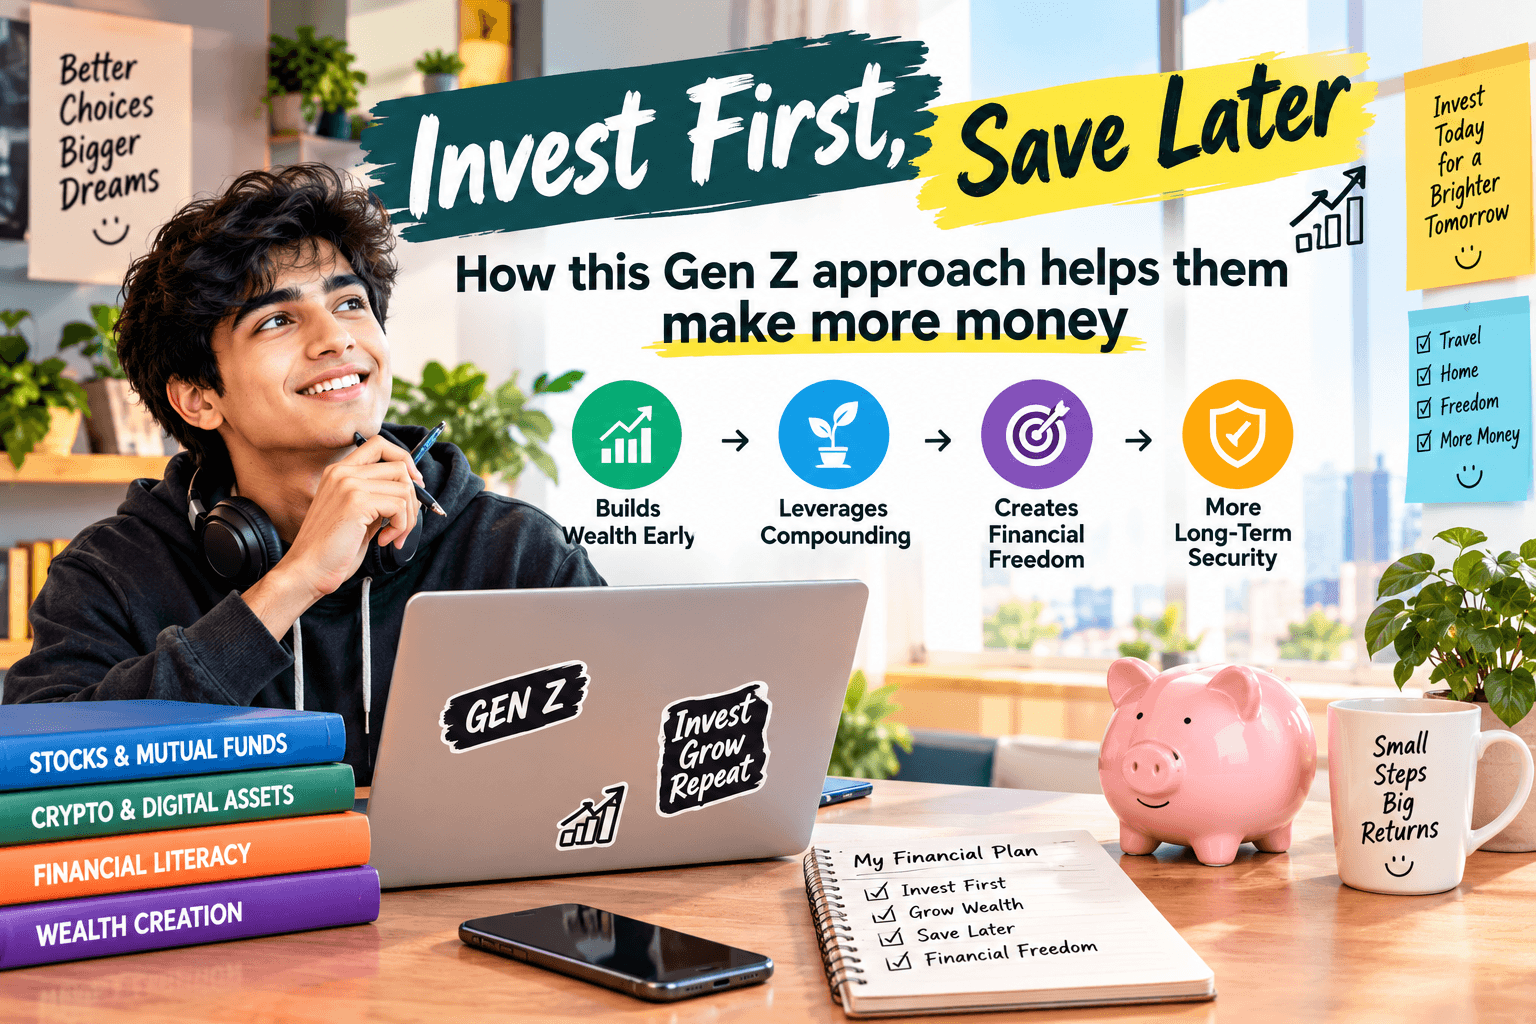
Young investors of Gen Z choose to invest the money they receive, instead of saving it first. This change in sequence changes the total amount of money one will possess in the future.
What does “invest first” mean?
The previous principle assumed that one had to accumulate money in the bank and invest what is left, after expenses. Investment became the additional step one could undertake after all necessary actions have been done.
The new principle implies that a specific percentage of one’s salary must be immediately used for investments and cannot be used for anything else (including parking it in the savings account).
Why has Generation Z inverted the principles
First, starting early allows the investments to maximise in terms of compounding.
There is also the issue of trust to be considered here. Interest rates of banks and other financial institutions are too meagre to overcome inflation. Young workers perceive the stock markets as more reliable ways to multiply money over decades.
Moreover, increased access to the market is also helping. Demat accounts can be opened in a few minutes now, without the hassle of paperwork, as earlier.
Mathematics of investing before saving
Let’s look at two people on the same salary. One invests whatever remains at the end of the month (almost always an inconsistent amount, not to forget the possibility of zero as well). The other person invests a certain amount of money the day she receives her salary, managing with what’s left.
Over ten or fifteen years, one not only invests more, but also spends much more time in the market.
Therefore, the money that is invested earlier in the month becomes more valuable in comparison with that invested later in the month.
That is why the order of actions matters as much as the amount itself.
Risks of such strategy
However, this strategy carries risks as well. Investing first without keeping something for emergencies means that one can be caught out in case he/she loses their job or have an unexpected, large expense.
It should also be remembered that stock markets fluctuate. In case there is an inadequate amount to work with, one can be obliged to sell the investments at a loss to cover their unexpected expenses.
How to invest first without becoming vulnerable
The wiser strategy is not to skip saving but to automate both. At least some emergency fund (three to six months) should be created before prioritising investments. Investors can also use a systematic investment plan calculator.
The smart way to go about it is to allocate a higher percentage of the total amount you can invest to a savings/liquid fund while simultaneously allocating to a pure investment fund.
This allows you to also benefit from the power of compounding. Once the liquid fund reaches your three-to-six-month expenses amount, you can stop investing in the liquid fund and proceed with 100% allocation to the investment fund.
You can automate both with systematic investment plans (SIPs). This strategy allows one to invest first in a disciplined way without neglecting the safety of savings. Also, choose the best platform for SIP investments.
Conclusion
Investment first does not mean skipping savings. It is simply adjusting your priorities. Generation Z chooses this strategy as it means more consistent investment, more time in the market, along with the creation of a safety net.